
Japan InsurTech Landscape 2026
A current view of the technology companies, digital insurance ventures and international players shaping insurance in Japan.
Free to download. No email or registration required.
Japan InsurTech Chaos Map 2026.
Twenty-five companies, placed into six functional categories and marked by company type — independent InsurTech, insurer-owned digital venture, international player active in Japan, or established/adjacent technology enabler.
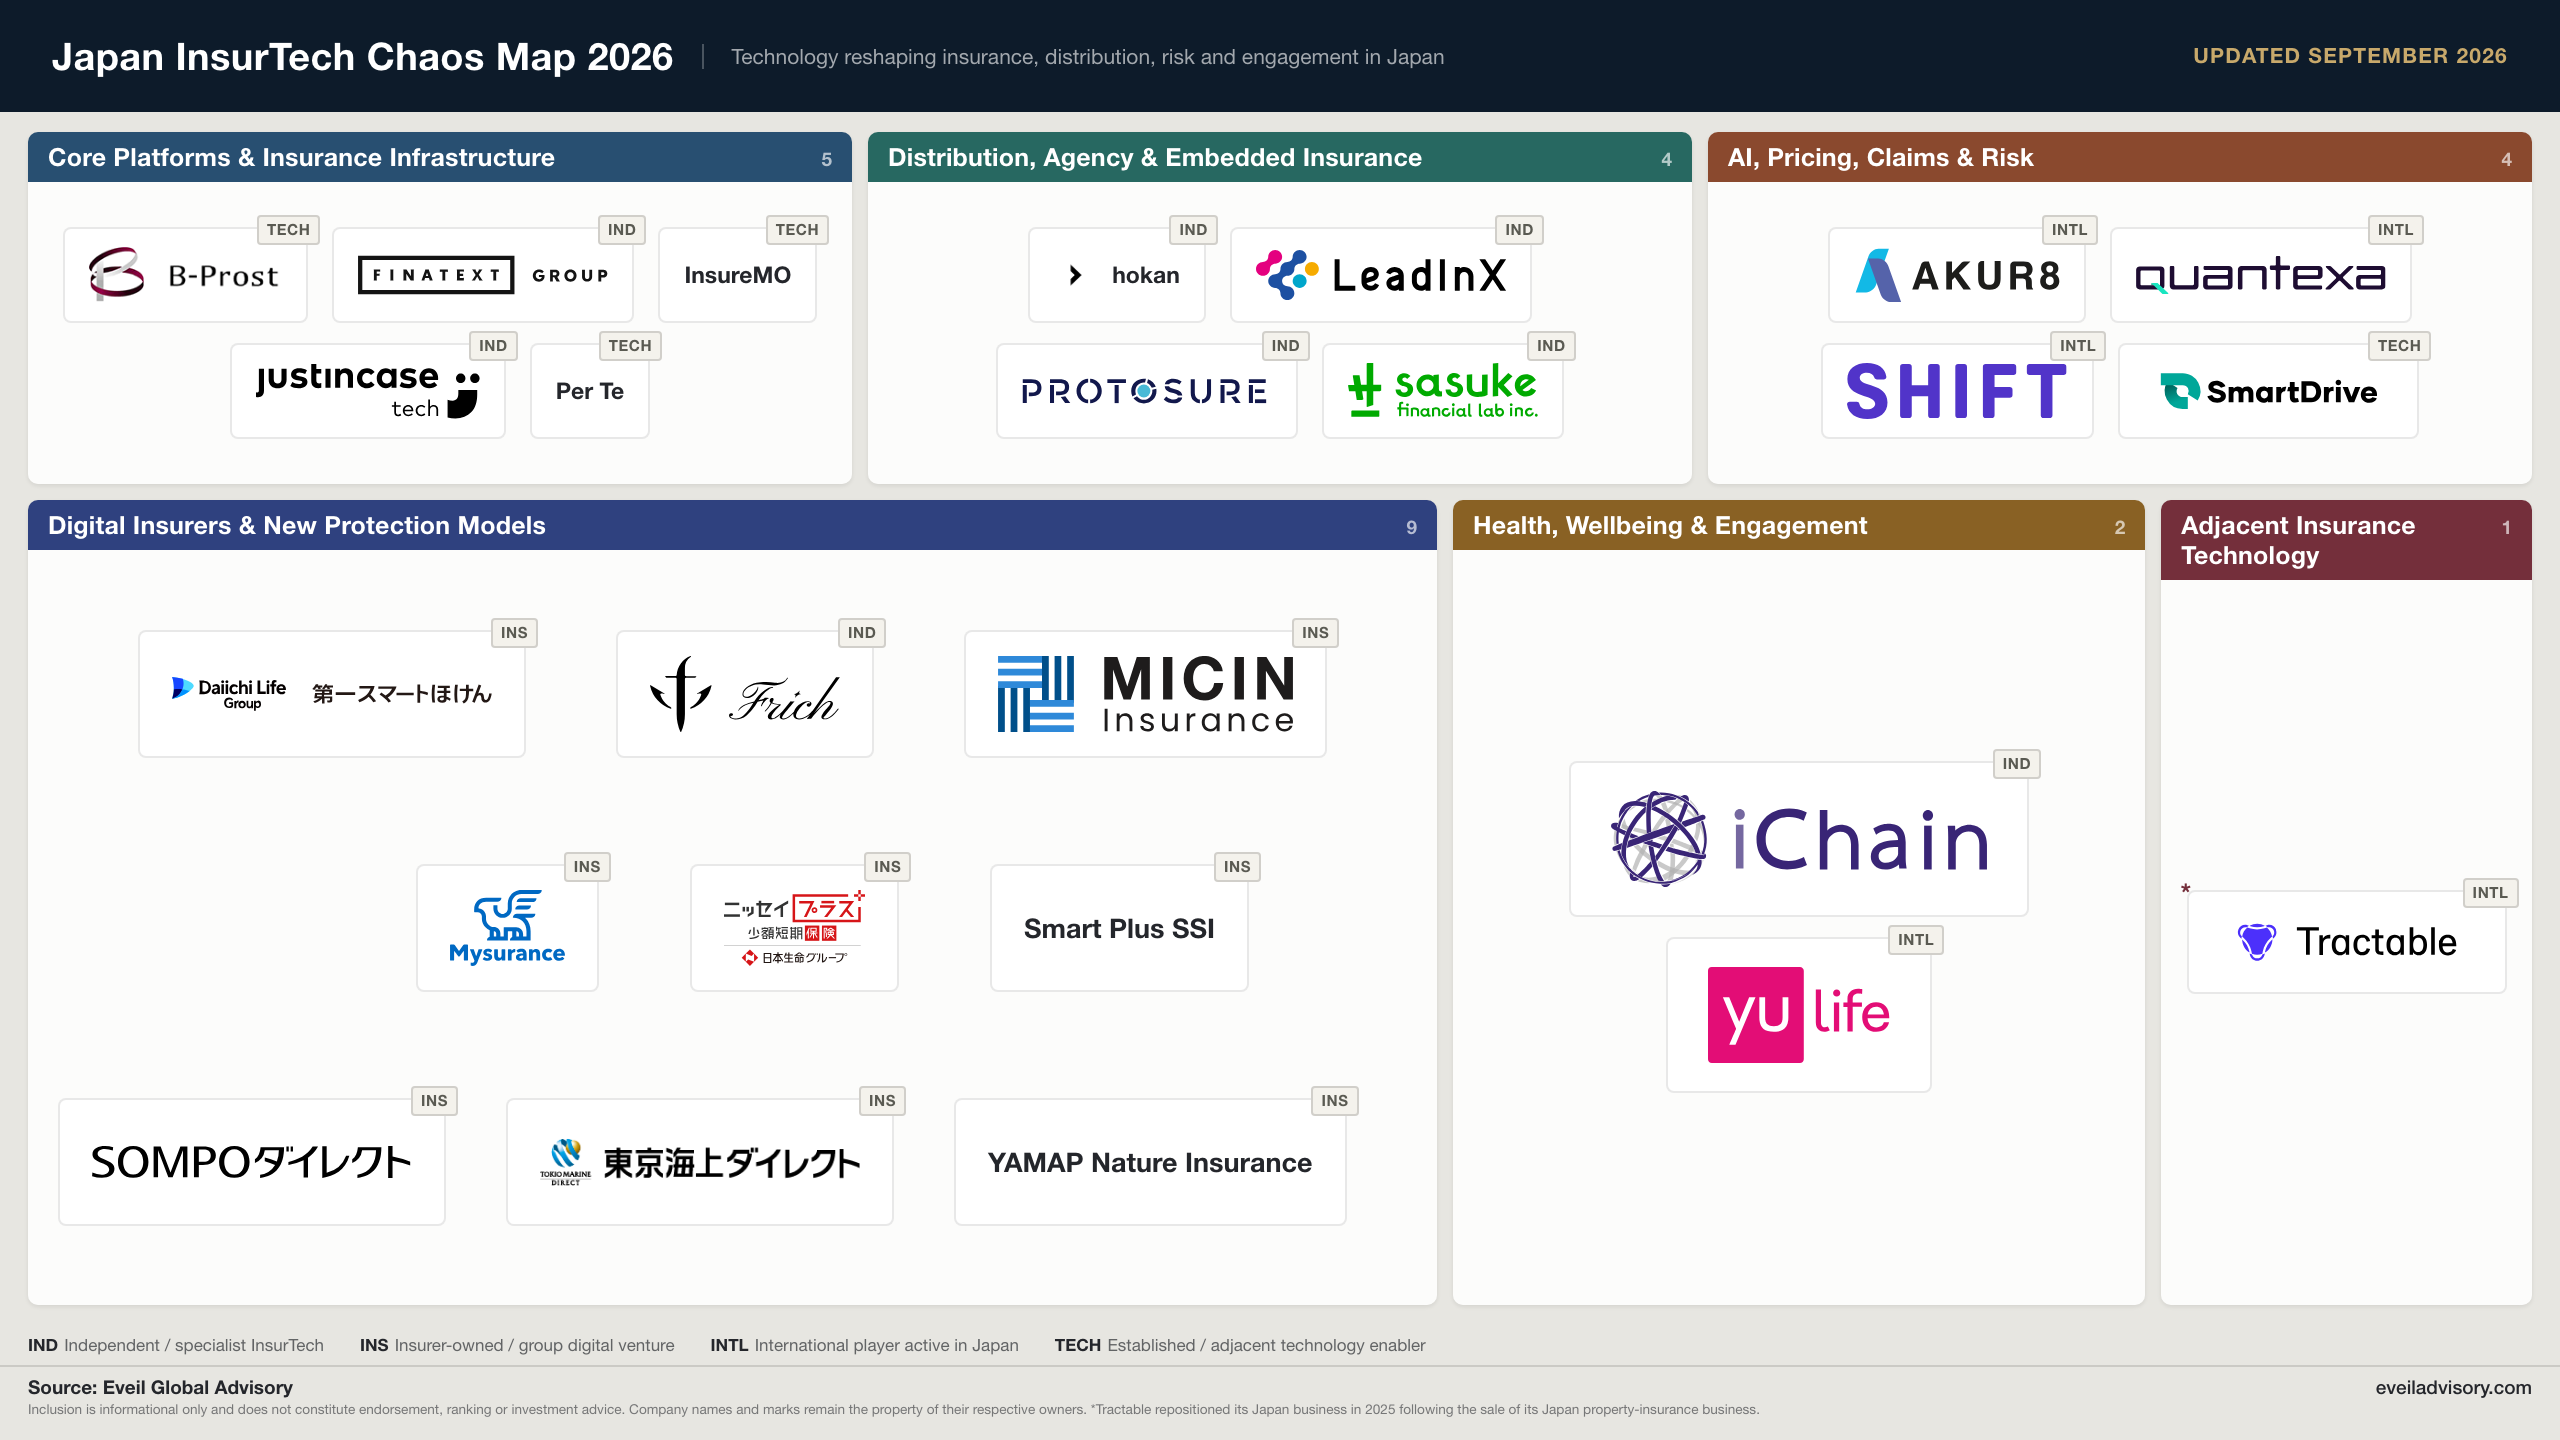
Select the map to open the full-resolution image. A permanent copy of this September 2026 edition is separately archived at /downloads/japan-insurtech-chaos-map-2026.pdf — the download button above always resolves to the current edition.
What the map covers.
The map covers Japan-native InsurTech companies, insurer-owned or group-affiliated digital ventures, established insurance technology providers, and a small number of international companies with material, publicly verifiable activity in the Japanese market.
What this is not
It is not a ranking. It is not an endorsement of any company named. It is not intended as an exhaustive list of every technology supplier to the Japanese insurance industry — it is a curated, evidence-based selection against a stated inclusion threshold, explained in full under Methodology below.
Twenty-five companies, six categories.
IND Independent / specialist InsurTech · INS Insurer-owned / group digital venture · INTL International player active in Japan · TECH Established / adjacent technology enabler
Core Platforms & Insurance Infrastructure
Policy administration, rating and core insurance systems.
- B-ProstTECH
- FinatextIND
- InsureMOTECH
- justInCase TechnologiesIND
- Per TeTECH
Distribution, Agency & Embedded Insurance
Agency tools, embedded distribution and broker technology.
- hokanIND
- LeadInXIND
- ProtosureIND
- Sasuke Financial LabIND
Digital Insurers & New Protection Models
Digital-first insurers, insurer-owned ventures and new protection models — the largest category in the current edition.
AI, Pricing, Claims & Risk
AI-driven underwriting, pricing, claims and risk analytics.
- Akur8INTL
- QuantexaINTL
- Shift TechnologyINTL
- SmartDriveTECH
Health, Wellbeing & Engagement
Health data, wellbeing and engagement platforms connected to insurance.
Adjacent Insurance Technology
Technology adjacent to core insurance, included only where Japan relevance is material and publicly verifiable.
- TractableINTL*
*Tractable repositioned its Japan business in 2025 following the sale of its Japan property-insurance business.
Five observations from the current edition.
The ecosystem extends beyond venture-backed startups
Established insurance-specialist technology vendors and large system providers — B-Prost, Per Te, InsureMO/NTT DATA — are a visible, distinct part of Japan’s real insurance technology stack, not only newer venture-funded entrants.
Insurer-owned digital ventures are a meaningful share
A substantial portion of the map’s companies are group-owned digital ventures rather than independent startups — concentrated in Digital Insurers & New Protection Models.
Digital Insurers & New Protection Models is the largest category
Nine of the current edition’s 25 companies sit in this category — more than any other, in the current edition.
International players are visible in AI, pricing, claims and risk
Three of the four companies in AI, Pricing, Claims & Risk are international firms with verified Japan activity, a different pattern from the more Japan-native composition elsewhere on the map.
Insurance increasingly intersects with health and wellbeing
Health, Wellbeing & Engagement is a small but distinct category on this map, reflecting insurance’s growing connection to health data and engagement platforms.
These are observations about the current edition’s composition, not claims about market share, growth or causality — none of which this map measures.
How companies are included.
This landscape is independently researched and classified by Eveil Global Advisory using publicly available primary sources and Eveil’s stated inclusion criteria.
Core inclusion test. A company or product must materially digitise or reshape at least one insurance value-chain activity. Generic technology vendors are excluded unless they have a clearly insurance-specific proposition and sustained relevance to the Japanese market.
International-player threshold. A Japanese-language site or conference attendance alone is not sufficient. Inclusion requires public evidence of Japan customer deployment, a Japan office or leadership, a named strategic partnership, an acquisition, or comparable sustained go-to-market activity.
Digital-insurer test. A digital insurer is not included solely because it sells online. It is included where technology, embedded distribution, data, or a materially different operating model is central to how it works.
Established-vendor treatment. Insurance-specialist technology vendors with a material, current product in the Japanese market can be included alongside venture-backed startups, marked by company type rather than excluded for being an established business.
Adjacent technology. Cross-industry technology providers are included only where their insurance-specific offering and Japan presence are both material and evidenced — kept to a strict threshold so this category does not become a generic enterprise-technology list.
Live-map policy. A company confirmed to have exited the Japan market is removed from the live map rather than carried indefinitely. Repositioning — a change of scope or focus short of a full exit — is noted against the company rather than treated as an exit, as with Tractable above.
Evidence standard. Inclusion is based on official company and product pages, official announcements, regulator or industry-association records, and customer announcements. Secondary sources are used for discovery, not as the basis for inclusion.
Freshness. Every entry is checked against current public evidence as of the edition date shown above. The intention is a quarterly review; this page states plainly when it was last updated rather than implying a cadence not yet operationally proven.
What has changed, by edition.
September 2026 — Initial publication. First public edition: 25 companies across six categories.
Future entries will record changes using the same categories every time: Added, Removed, Acquired, Exited Japan, Repositioned, Renamed, or Category changed — so a returning reader can see exactly what moved between editions rather than only a new company count.
How to reference this map.
Suggested citation:
Eveil Global Advisory, Japan InsurTech Landscape 2026, updated September 2026.
Please link to the canonical Japan InsurTech Landscape page when referencing this map:
This HTML page, not the PDF, is the citable and linkable reference: it is the canonical, permanently maintained version, while the PDF is a point-in-time download of one edition.
For reference only. Inclusion does not imply endorsement or ranking.
Need to understand a specific part of the Japanese insurance market?
This map is a starting point for orientation, not a substitute for work scoped to a specific question — a category, a company, or a decision this landscape raises for you.